Shrinkflation: Paying More, Getting Less… and Doing More of the Work
News
|
Posted 03/11/2026
|
211
Key Takeaways
- Shrinkflation hides a price rise by shrinking what sits inside the packaging.
- Self-service shifts work from businesses to customers, who still pay full retail.
- Card surcharges ended on 1 October 2026, but the payment costs did not.
- Investors hold gold and silver to preserve purchasing power, not to get rich.
I recently felt the beginnings of a flu. Like many Australians, I headed to the supermarket in search of one of life’s simplest comforts: a box of Twinings Decaffeinated Green Tea. Standing in the tea aisle, however, I encountered something far more shocking than my symptoms.
For years, I’d bought the familiar box containing 100 tea bags. This time, it contained just 80. The packaging looked almost identical, and the price was much the same as I remembered. It wasn’t until I looked closely that I realised 20 tea bags had quietly disappeared. It struck me this wasn’t really a story about tea. It was a story about the Australian economy. Welcome to shrinkflation.
How shrinkflation hides a price rise
Manufacturers have become remarkably adept at avoiding obvious price rises. Rather than increase the shelf price by 20 per cent, they reduce what’s inside the package. The cereal box gets narrower, the chocolate block loses a few rows, and the biscuit packet contains fewer biscuits. Consumers notice higher prices, but smaller quantities can slip under the radar. CHOICE found Cadbury’s largest box of hollow Easter eggs shrank 68 grams and rose A$5.50 between 2024 and 2026, close to 73 per cent more per 100 grams (CHOICE, March 2026).
Inflation, it seems, has become something of a magician. Instead of making prices visibly larger, it makes products invisibly smaller.
Of course, businesses face many of the same pressures as consumers: higher wages, energy costs, transport expenses and raw materials. In many cases, reducing package sizes attracts less customer resistance than raising prices outright. Shrinkflation is as much about consumer psychology as economics.
The service economy shrank too
And it isn’t confined to supermarket shelves. The service economy has embraced its own version.
Not so long ago, supermarkets employed rows of checkout operators. Today, customers increasingly do the work themselves. We scan every item, weigh our fruit and vegetables, bag our purchases, troubleshoot scanner errors and occasionally wait for staff approval because the machine suspects we’ve committed grand theft by placing onions in the bagging area too quickly. Having done what was once paid work, we then pay full retail price.
Yet we’ve gradually accepted similar arrangements throughout the retail economy.
Fast-food outlets encourage us to order through touchscreens. Airlines expect us to check ourselves in. Hotels encourage guests to check themselves out. Banks close branches while steering customers towards online banking, with 3,108 left at 30 June 2026, down 3.0 per cent in a year (APRA, 14 October 2026). Customer service increasingly begins with an artificial intelligence chatbot that seems determined to answer every question except the one we actually asked.
Technology undoubtedly delivers efficiencies. But some of those efficiencies come from shifting work from businesses to customers. We’ve quietly become unpaid employees.
What happened to the card surcharge?
Then comes another irony: the card surcharge. After scanning our own groceries, packing our own bags and doing much of the retailer’s work, we were often charged extra simply for paying by card.
Since 1 October 2026, Australian businesses have been prohibited from imposing separate surcharges on payments made using Visa, Mastercard, eftpos and American Express cards, after the RBA removed its prohibition on no-surcharge rules and those networks introduced no-surcharge rules of their own (RBA, Removal of Card Payment Surcharges FAQs). But the costs of accepting electronic payments haven’t disappeared. Businesses may recover those costs through their general prices rather than adding a separate surcharge at the checkout.
What this means for purchasing power
Viewed individually, these changes may seem insignificant. Together, they reveal a broader pattern: products become smaller, services become leaner, customers do more for themselves and costs become less visible. The cumulative effect is that consumers can pay more while receiving less. Inflation isn’t simply about rising prices; it’s also about what our fiat[1] currency can actually buy.
Sometimes prices rise. Sometimes quantities shrink. Sometimes quality declines. Sometimes services disappear. Increasingly, consumers experience several of these at once.
Why gold and silver sit in this conversation
For long-term investors, this raises a fundamental question: how do we preserve purchasing power over decades rather than simply chase investment returns from year to year? This helps explain why gold and silver continue to occupy a unique place in financial history.
Unlike fiat currency, precious metals cannot simply be created at the press of a button. New supply depends on exploration, mining, energy, labour and capital. Their scarcity is physical rather than political.
For thousands of years, gold (and silver) has served as money or a store of wealth across civilisations separated by geography, language and centuries. Historical comparisons are never exact, but gold has maintained a remarkable reputation for preserving wealth over long periods.
Currencies, by contrast, have changed repeatedly. Empires have risen and fallen, monetary systems have evolved and paper currencies have come and gone. Gold has continued to be recognised around the world as a store of wealth, although its market price and purchasing power can fluctuate considerably.
For much of modern history, gold also played a direct role in the monetary system. Following the Second World War, the international monetary system was built around the US dollar. Under this post-war arrangement, the dollar was convertible into gold at a fixed price of US$35 per troy ounce for foreign governments and central banks, while several other currencies were linked to the dollar.
That changed on 15 August 1971, when US President Richard Nixon suspended that convertibility (US Department of State, Office of the Historian). The post-war system subsequently broke down, and the world moved towards the monetary arrangements we know today, in which currencies are not generally redeemable for a fixed quantity of gold.
Modern fiat currency derives its value from public confidence, government and central bank policies, and the productive strength of the economy that issues it. Unlike gold, the supply of fiat currency can be increased through monetary and financial systems. When people and businesses have more fiat currency to spend than the economy can produce in goods and services, prices can rise and each dollar buys less.
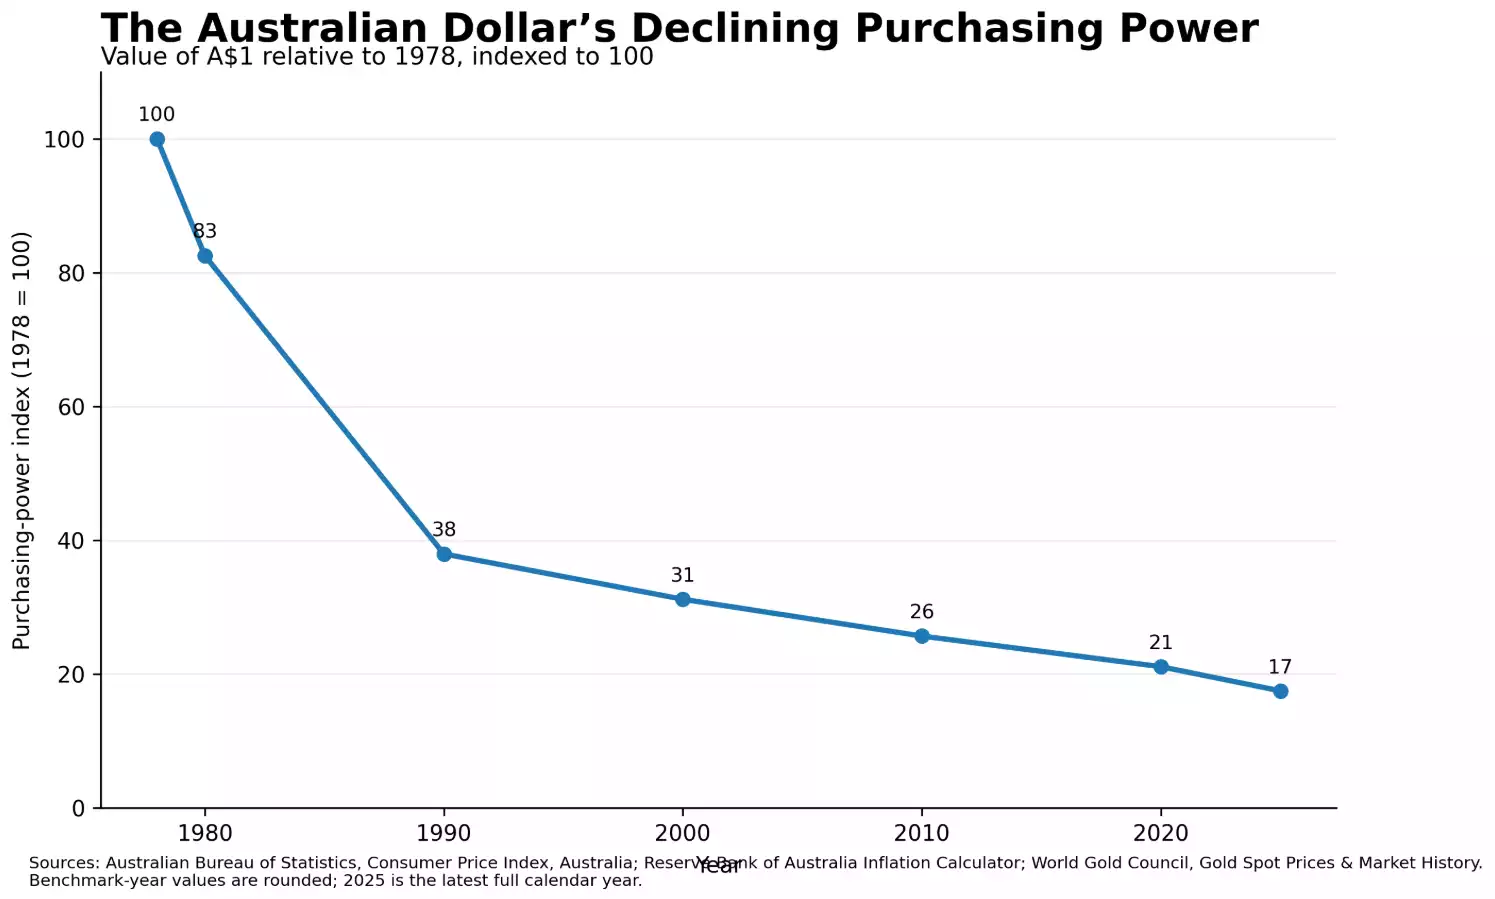
Australia has experienced a substantial erosion of purchasing power over the decades. A basket costing A$100 in 1978 cost about A$650 by 2025 on ABS Consumer Price Index calendar-year averages, the method the Reserve Bank uses in its own inflation calculator (ABS CPI series, 1978 and 2025). A hundred dollars still bears the same number printed on the note, but it buys considerably less than it once did. The face value hasn’t changed; its real purchasing power has.
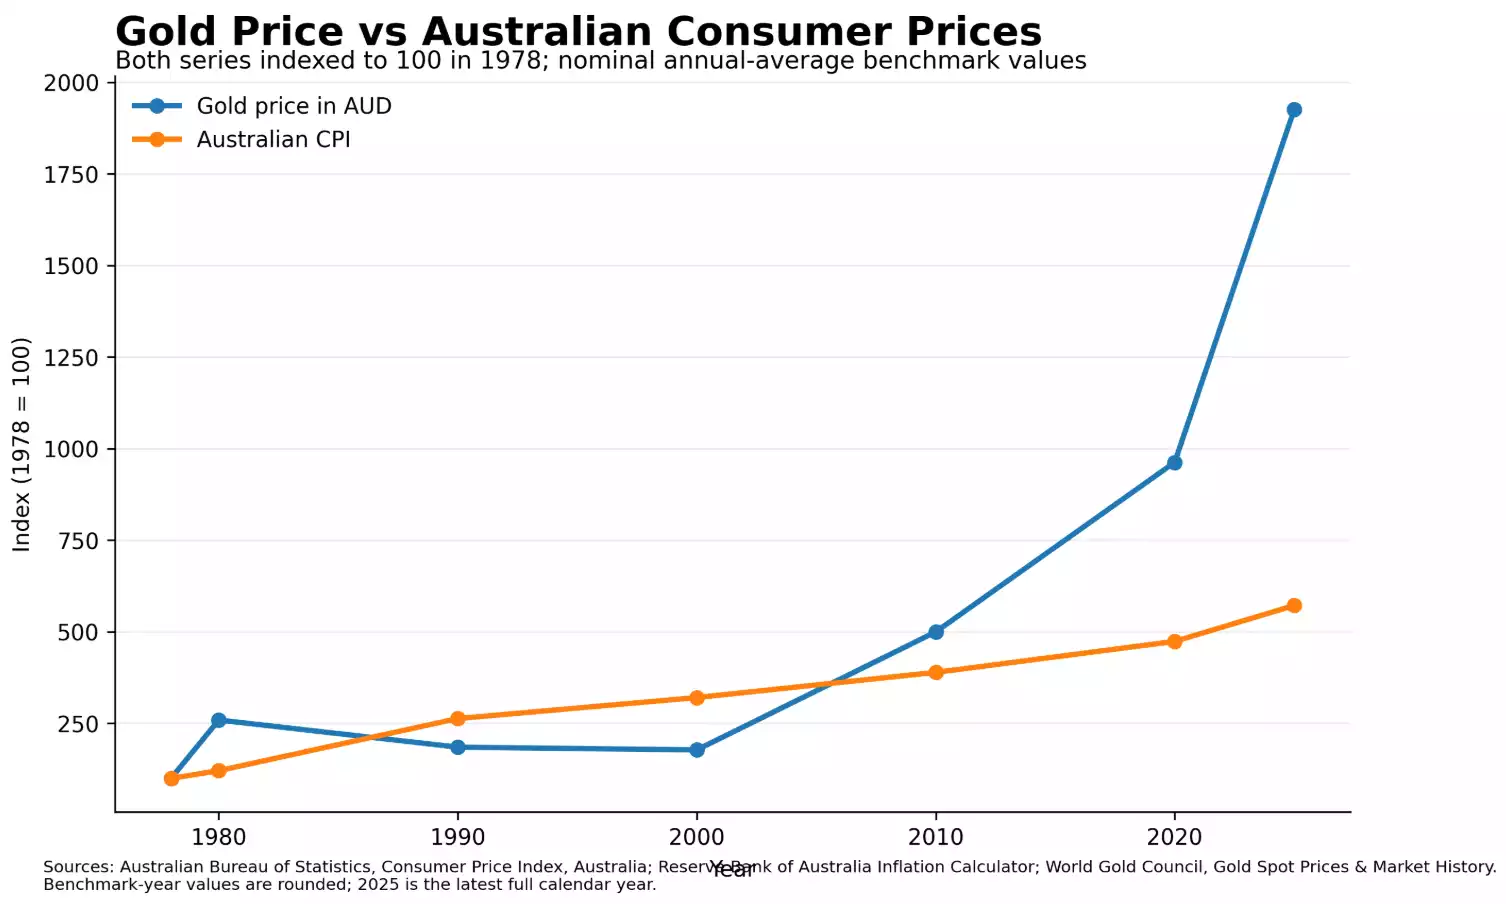
History offers many examples of currencies losing purchasing power over time. Today’s world exhibits some of the same pressures: government debt levels are high, budget deficits are commonplace, and increasing the supply of fiat currency remains one response to economic weakness. These factors can contribute to inflation and, in some circumstances, weaken confidence in a currency.
None of this guarantees that gold or silver prices will rise tomorrow, next month or even next year. Precious metals can experience extended periods of limited returns and can be volatile over shorter timeframes. Rather, many investors don’t own precious metals because they expect to get rich. They own them because they believe they may help preserve wealth over the long term.
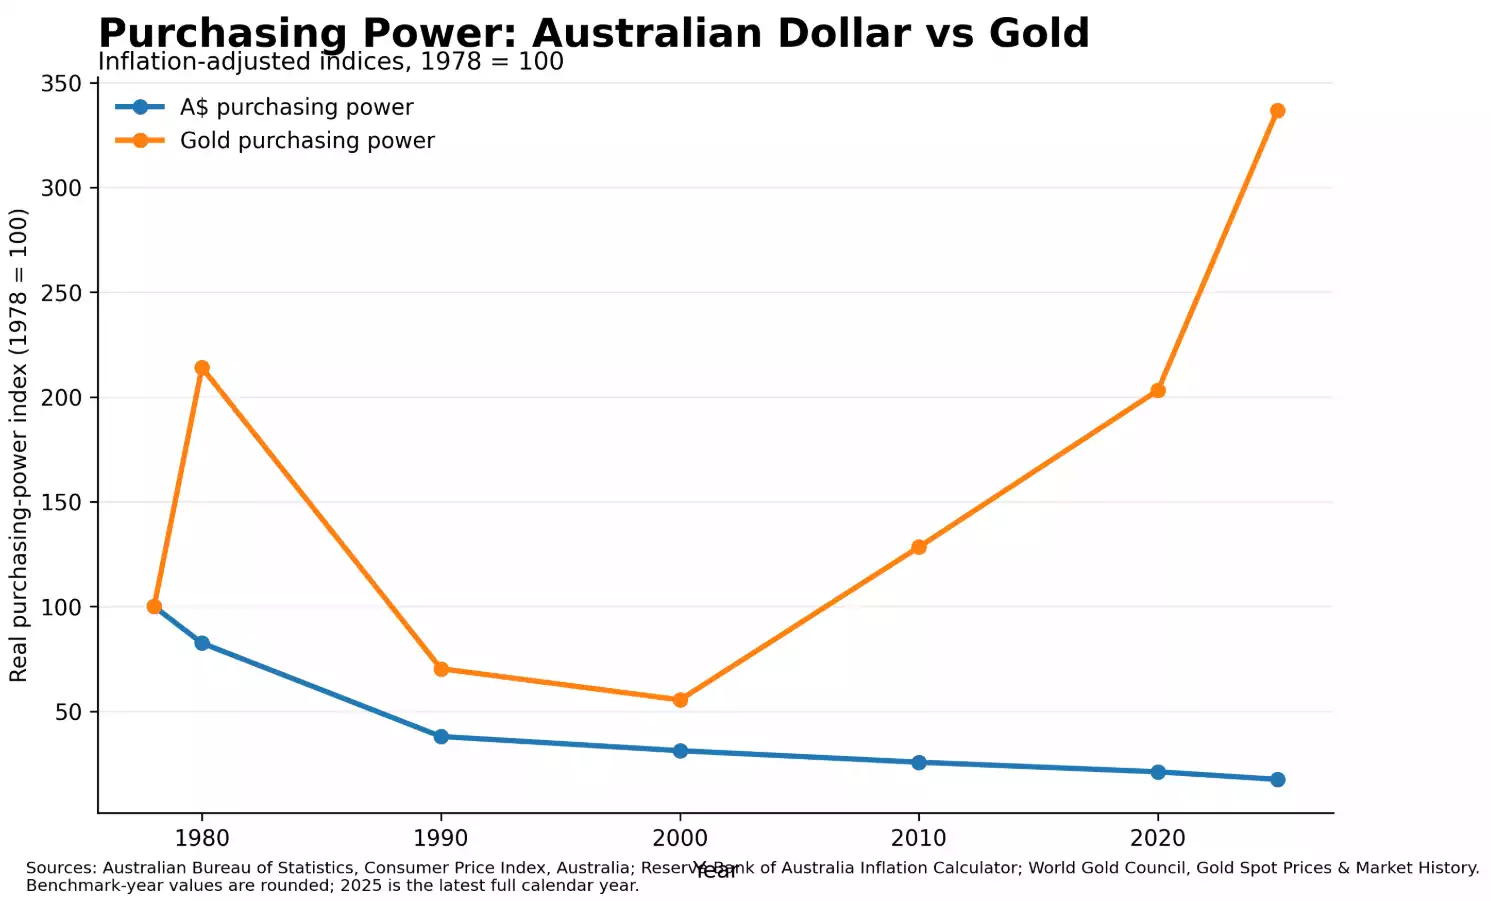
Perhaps my visit to the tea aisle was never really about 20 missing tea bags. It was about value quietly disappearing: tea bags, checkout operators, customer service and purchasing power. These changes rarely happen overnight. They accumulate gradually, almost invisibly, until one day we realise we’re paying more, receiving less and wondering where the difference went.
What it means for investors
That raises a question worth asking: twenty years from now, what will our savings actually buy?
For investors thinking about inflation, purchasing power and the role of precious metals, the team at Ainslie Bullion can help explain how gold and silver might fit into a portfolio, not as get-rich-quick investments, but as potential long-term stores of wealth and a form of financial insurance. For those who prefer to accumulate steadily, there is Ainslie Saver.
Sometimes the most valuable investment isn’t the metal itself, but the knowledge that helps you decide whether it belongs in your portfolio.
[1] A fiat system is one where a currency is not backed by a physical commodity such as gold, but by a government directive making it legal tender (RBA, What is Money?).
_______________________________________________
This article is general information only and does not constitute financial advice. Past performance is not indicative of future results. Always conduct your own research or consult a licensed financial adviser before making investment decisions.