Macro Turning Point For Bonds and Precious Metals
News
|
Posted 07/10/2026
|
1127
Key Takeaways
- Markets price the Fed holding rates steady at its late October meeting.
- Bond yields look to be topping after a long run higher.
- Lower rates have historically supported gold and silver prices.
While bond yields have been on a tear, rising and forcing the central banks to raise rates, it appears they are currently topping out, with the markets pricing in "no-rate-hikes" for the upcoming Fed meeting late October. The US Fed raised its target range by 25 basis points to 3.75 to 4.00 percent on 16 September 2026, its first increase since 2023 (Federal Reserve, 16 September 2026), and fed funds futures put roughly 82% odds on no change at the 27 and 28 October 2026 meeting (Central Bank Watch, 6 October 2026).
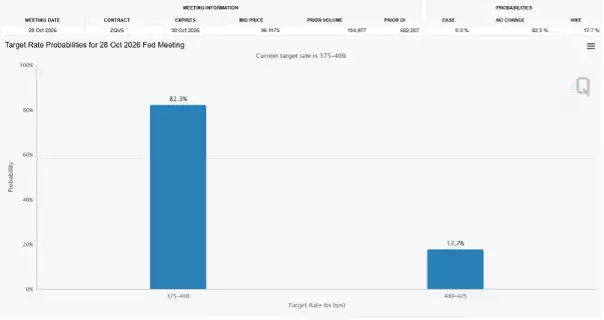
While the expectation for yields topping can be built around the long term bond cycles bottoming (inverse relationship to yields), the markets interest rate expectations add another layer of confluence to this macro view.
While this is good news for debt repayments for individuals and governments, it's a concern for stock investors, as a pause tends to arrive when the economy is slowing. US unemployment lifted to 4.2% in September 2026 with payrolls adding only 29,000 jobs, while CPI was still running at 3.4% over the year to August 2026 (St Louis Fed, October 2026, BLS, 11 September 2026).
A response by central banks to loosen too late could result in stocks pulling back while investors pile into safety assets such as bonds and metals.
As buyers step in for US bonds to stabilise the downtrend in collaterals (or the uptrend in bond yields), we can see market participants hedging for a trend reversal. The 10 year yield eased to 5.26% on 6 October 2026, after reaching its highest level since 2002 (Trading Economics, 6 October 2026).
Meanwhile, sentiment on bonds is at a record low, marking major turning points. The Bond Daily Sentiment Index fell to 10% in early October 2026, deeply pessimistic territory, as the 30 year yield ran from 5.25% to 5.69% over seven trading sessions. BTIG's Jonathan Krinsky read that as yields approaching the limit of their tactical upside (BTIG via TechFlow, October 2026).
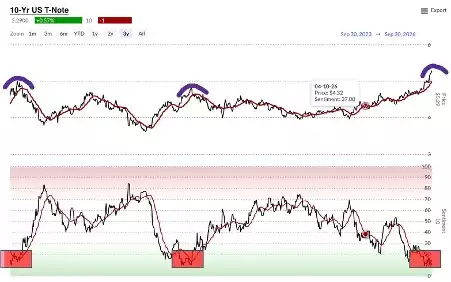
Interest rates and bond yields are inextricably linked as central banks cannot cut rates while yields are moving up, to keep the bond market stable. With yields looking to top, the market is aptly anticipating interest rate hikes to cease.
The counter case is that a pause is not a peak. Sixteen of eighteen FOMC participants projected at least one further increase this year in the September 2026 projections, and futures pricing still carries another hike into December 2026 rather than cuts (Wells Fargo Advisors, September 2026, Polymarket odds, 3 October 2026).
Lower rates are historically good for precious metal prices, as falling real yields reduce the incentive to hold cash and bonds.
As both gold and silver emerge from their macro Half Cycle Lows this year (4 years into an 8 year cycle, which started in October 2022), lower rates could pour gasoline on the macro multi year bull run, for both metals.
As participants hedge for stock market instability and monetary tightening looks to be pausing, both gold and silver emerge from their half cycle lows in ideal conditions for a continued macro bull run. Ainslie Bullion has been helping Australians accumulate physical gold and silver since 1974, and a thesis measured in years tends to favour buying through the cycle rather than timing a single entry.
_______________________________________________
This article is general information only and does not constitute financial advice. Past performance is not indicative of future results. Always conduct your own research or consult a licensed financial adviser before making investment decisions.